Many people assume that life insurance and annuities serve the same purpose because both are offered by life insurance providers. However, understanding the difference between life insurance and an annuity is important before making any long-term financial decision. While life insurance focuses on protecting your loved ones financially, an annuity is designed to provide you with a regular income, usually after retirement. Although both products support financial planning, they address different needs and work in different ways. Knowing how each works, along with its tax treatment, can help you make informed financial choices.
What Is Life Insurance?
Life insurance is a financial product that provides a payout to your nominated beneficiaries if you pass away during the policy term or according to the policy conditions. Its primary purpose is to provide financial support to your family so they can manage day-to-day expenses, repay outstanding liabilities, or continue working towards important financial goals.
Some life insurance products also include a savings or investment element. However, the core objective remains financial protection. Several insurers, such as Aviva India, offer different types of life insurance solutions to meet varying financial needs. The right option depends on factors such as your age, financial responsibilities, number of dependants, and long-term objectives.
Many individuals consider life insurance when they start earning, get married, purchase a home, or begin planning for their family’s future. Choosing an appropriate level of cover can help ensure that your loved ones have financial support even if they face the unexpected.
What Is an Annuity?
An annuity is a financial product that provides a regular income to the person who purchases it. It is commonly used as a source of income after retirement, helping individuals meet ongoing living expenses once they stop receiving a regular salary.
You may purchase an annuity by investing a lump sum or by making contributions, depending on the product. In return, you receive payments at agreed intervals for a fixed period or throughout your lifetime, based on the chosen plan and its terms.
Unlike life insurance, where the financial benefit is intended for your beneficiaries, an annuity focuses on supporting your own financial needs. The predictable income can help cover routine expenses such as household costs, healthcare, and other day-to-day requirements during retirement.
The amount you receive usually depends on factors such as the amount invested, the selected payout option, and the terms of the annuity. As a result, annuities are generally viewed as an income solution rather than a financial protection product.
Difference Between Life Insurance and Annuity
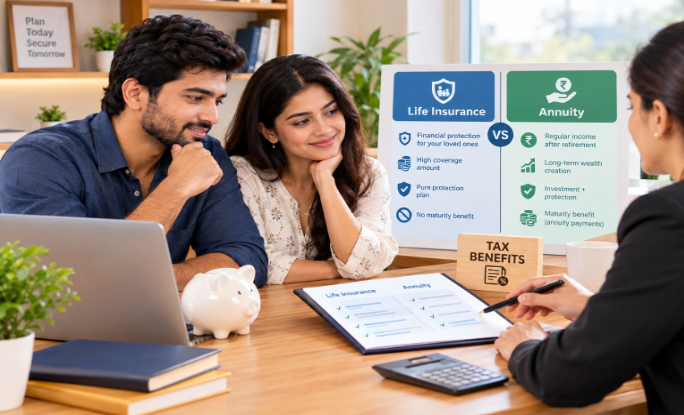
The difference between life insurance and an annuity becomes clearer when you compare their purpose, beneficiaries, and payment structure. Although both contribute to long-term financial planning, they are designed to achieve different outcomes.
| Aspect | Life Insurance | Annuity |
| Primary purpose | Provides financial protection for your family | Provides regular income to the policyholder |
| Benefit recipient | Nominee or beneficiary | Policyholder |
| When benefits are paid | Usually after the policyholder’s death or according to the policy terms | During the policyholder’s lifetime based on the selected payout option |
| Payment structure | Lump sum or policy-specific benefit | Regular income at agreed intervals |
| Financial objective | Supports dependants financially | Supports retirement income |
| Typical need | Family protection and financial security | Income during retirement |
Tax Benefits Explained
The tax treatment of life insurance and annuities differs because they are designed for different financial objectives. The key tax considerations are:
- Life Insurance Premiums: Eligible premiums may qualify for deductions under Clause 123 of the Income-tax Bill, 2025, which corresponds to the earlier Section 80C of the Income-tax Act, 1961. If you are looking for information about 80C life insurance, it is important to understand that these deductions are generally available only when the applicable conditions under the relevant tax regime are satisfied.
- Life Insurance Benefits: Eligible death benefits remain exempt under Clause 12 read with Schedule II of the Income-tax Bill, 2025, corresponding to the earlier Section 10(10D), subject to the prescribed conditions.
- Annuity Income: Regular payments received from an annuity are generally treated as taxable income under the applicable income tax provisions because they are paid directly to the policyholder. The exact tax treatment depends on the nature of the annuity and the prevailing tax rules.
Understanding these provisions helps you compare life insurance and annuities not only from a financial perspective but also from a tax planning point of view. Reviewing both the financial purpose and the applicable tax treatment can help you make a more informed decision.
Conclusion
Life insurance and annuities may both contribute to long-term financial planning, but they serve different purposes. Life insurance helps provide financial security for your loved ones if you are no longer there, while an annuity is intended to provide you with a regular income, particularly during retirement. Their tax treatment also differs because of these distinct objectives. Understanding these differences can help you evaluate which option aligns with your financial priorities, family responsibilities, and future income requirements before making a long-term financial commitment.